Company Incorporation Guide
Uruguay company incorporation for foreign founders
Applicable country/region: UY - Uruguay
- Written by our advisory team
- Uruguay rules and requirements
- Checked against official sources
Guide overview
From the company name to the first filings
Uruguay company incorporation means founders, natural or legal persons, Uruguayan or foreign, adopting a company's bylaws and registering it with the Registro Nacional de Comercio (RNC) of the Dirección General de Registros (DGR). The company exists in law once its contract is signed, but it is regularly constituted only once registered; until then a sole founder answers personally for its obligations. The company name comes first (the RNC checks it at registration; reserving it is optional), then the legal form. Next are the local conditions, the registration route the founders' make-up allows and how the cost is built. Registration opens the tax registrations and first duties; after it come the beneficial-owner filing, the bank account and the annual return.
COMPANY TYPES
Picking the S.A.S., S.A. or S.R.L. for Uruguay company incorporation
Reading the company types
Uruguay S.A.S Basic Information
Uruguay S.A.S Registered Capital Requirement
REQUIREMENTS AND ESTIMATED COST
How the founders set the route, and what the requirements mean
Reading the requirements
Base Cost
Requirements
To register a company in Uruguay, a commercial address in Uruguay is required. If you do not have a commercial address in Uruguay, you can choose TKEG Expat ™ (EU)'s Registered Address service.
Monthly tax filings are required once your company is created, even if your company does not have any operations/activities. If you do not have an accountant or accounting agency doing this for you, you can choose TKEG Expat ™ (EU)'s accounting service.
Estimated Cost
Add TKEG Expat ™ (EU) as a preferred source on Google
TAX
What the tax registration switches on first
Reading the tax data
Corporate Income Tax (CIT)
Withholding Tax (WHT)
Value-Added Tax (VAT)
Capital Gain Tax (CGT)
Effective Tax Rate (ETR)
Conclusion
Once registered: beneficial owners, the bank and the annual return
Under Ley 19.484, every S.A.S. files a sworn statement with the Banco Central del Uruguay (BCU) naming its shareholders and beneficial owners. Beneficial owners are natural persons with at least 15% of the capital or votes, directly or indirectly, or final control by other means. The statement is due within 45 days of formation, or 90 days with a non-resident holder or beneficial owner. The corporate bank account, a separate approval with its own identity checks, follows the RUT and that filing. Each year the shareholders approve the financial statements and the company files its annual return. The next step: trace any corporate founder to its natural persons before signing the bylaws, so the BCU filing is on time.
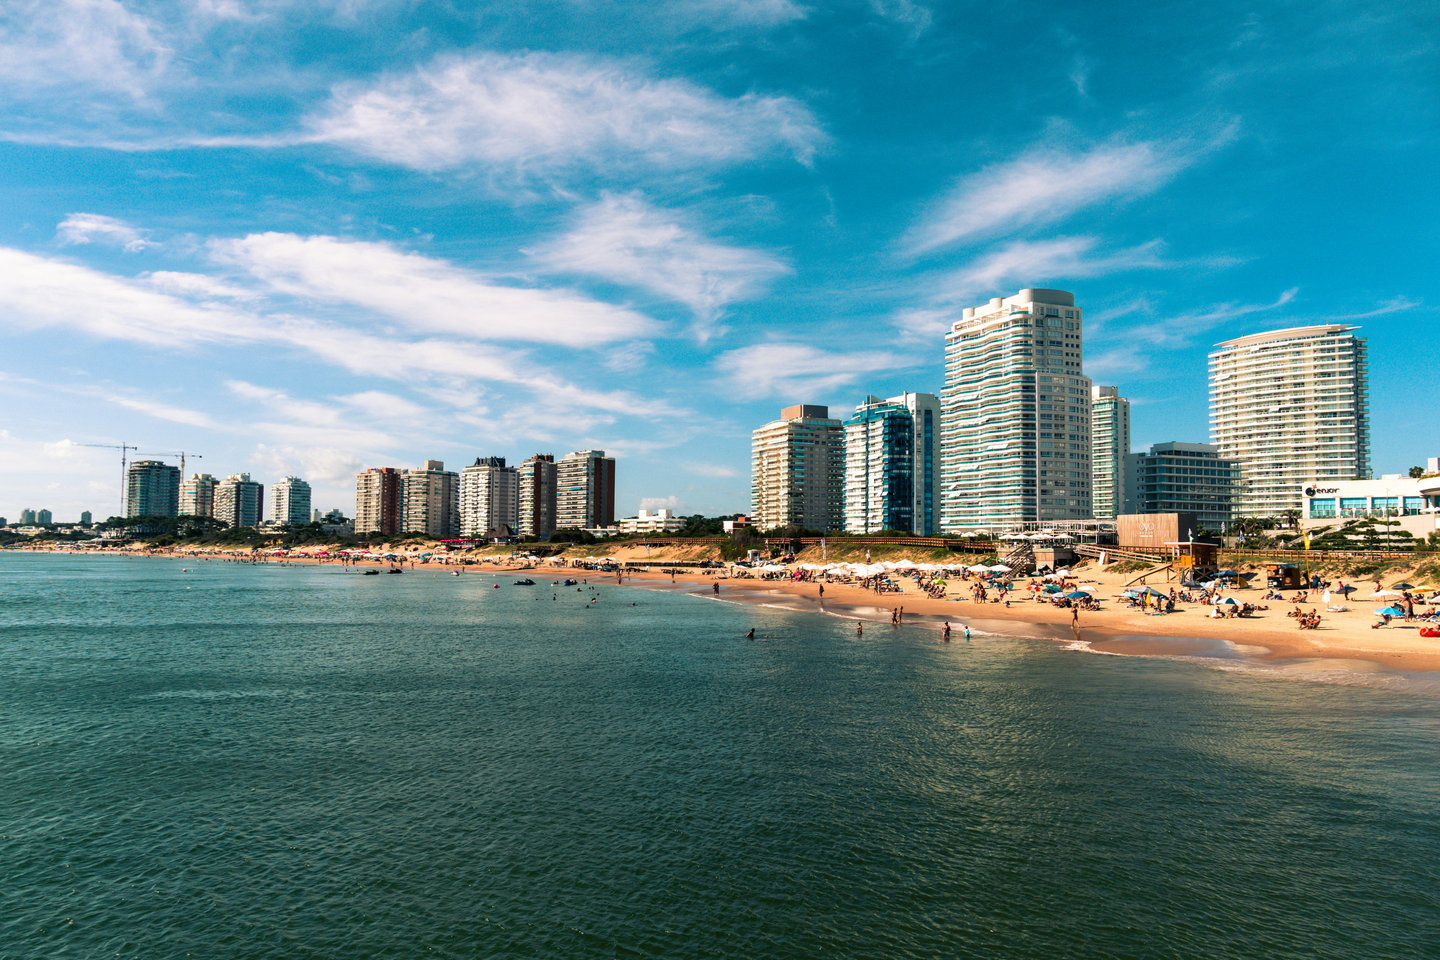
About Uruguay
Uruguay is South America’s most politically stable country with strong rule of law, a free trade zone regime offering full tax exemptions, and a strategic Mercosur location between Brazil and Argentina.
View Complete Information

 Argentina - Español
 Chile - Español
 Colombia - Español
 Costa Rica - Español
 España - Español
 Estados Unidos - Español
 Global - Español
 Mexico - Español
 Panama - Español
 Peru - Español
 Union Europea - Español
 中国内地 - 简体中文
 新加坡 - 简体中文
 泰国 - 简体中文
 澳大利亚 - 简体中文
 马来西亚 - 简体中文
 澳門特區 - 繁體中文
 香港特區 - 繁體中文


